%%{init: {'theme': 'neutral', 'themeVariables': { 'fontFamily': 'monospace', "darkMode":false, "fontSize":"16px"}}}%%

flowchart TD
    Start(["Do I need this money<br>within 6 months?"])
    Start -->|"Yes"| HYSA("High-Yield<br>Savings Account")
    Start -->|"No"| Q2{"Can I lock it away<br>for 3 to 60 months?"}

    Q2 -->|"Yes"| CD("Certificate<br>of Deposit")
    Q2 -->|"No"| HYSA

    HYSA --> HYSA_Details["Ally, Marcus, Capital One<br>About 4% APY<br>Access in 1 to 2 days"]
    CD --> CD_Details["Online banks, credit unions<br>About 4% APY<br>Penalty if withdrawn early"]

    style Start fill:#0e9aa7,color:#FFFFFF,stroke:#1C1C1E,stroke-width:2px
    style Q2 fill:#f0cfcf,color:#1C1C1E,stroke:#1C1C1E,stroke-width:2px
    style HYSA fill:#48a56a,color:#FFFFFF,stroke:#1C1C1E,stroke-width:2px
    style CD fill:#86ddcd,color:#1C1C1E,stroke:#1C1C1E,stroke-width:2px
    style HYSA_Details fill:#FFFFFF,color:#1C1C1E,stroke:#1C1C1E,stroke-width:1px
    style CD_Details fill:#FFFFFF,color:#1C1C1E,stroke:#1C1C1E,stroke-width:1px
7 High-Yield Savings Accounts
In Savings Strategies, I identified high-yield savings accounts (HYSAs) as the foundation for your savings, the place where your emergency fund and sinking funds live. In this chapter I’ll walk through how to pick one, open it, and use it well.1
7.1 Why a Separate Account Matters
The real reason to move your savings to a different bank isn’t the extra interest (though that adds up). It’s about your habits. Ramit Sethi points out that when your savings account is at a different institution, moving money back to spending takes 1 to 2 days and a few extra steps. That friction is what stops a midnight impulse purchase.
I’ve found that savings kept in the same checking account as your spending money don’t survive. You see the balance, and you spend it. This is one place where out of sight, out of mind works in your favor.
7.2 Choosing the Right Account (decision framework)
Different situations call for different account types. The diagram below walks through the choice with two questions.
Most people should start with a high-yield savings account. It’s the default for emergency funds and sinking funds because it balances three things: safety (FDIC-insured), liquidity (money available in 1 to 2 days), and return (around 4% APY in 2026, which usually beats inflation).
7.3 Comparing High-Yield Savings Accounts
All HYSAs share the same basic structure (they’re FDIC-insured and easy to reach), but they differ in rate, features, and bank reliability. The table below compares a few common options as examples. Rates change often, so it doesn’t list them: in late 2026 the best online savings accounts paid up to about 4.2% APY (NerdWallet), while the national average for savings accounts was 0.39% (FDIC). Always check the current rate before you open an account.
| Bank | Min Deposit | Features | Best For |
|---|---|---|---|
| Ally Bank | $0 | Clean interface, no fees, no minimums | Most people |
| Marcus by Goldman Sachs | $0 | Simple, no fees, no minimums | Keeping it simple |
| American Express HYSA | $0 | Tied to Amex cards and services | Amex card holders |
| Capital One 360 | $0 | Tied to Capital One cards and checking | Capital One users |
| Regular Bank (Chase, BoA) | $0 | Local branch access (you don’t need) | Avoid this; often 0.01% |
The differences between online banks are small: usually 0.1% to 0.4%. On a $10,000 balance, that’s $10 to $40 a year. The bigger point is that all of them pay far more than a big bank’s basic savings account: 4% is 400 times 0.01%.
You don’t need a checking account at the same bank. Most people open a HYSA at one online bank and keep checking at their current bank. Money moves between them in 1 to 2 days by ACH transfer (the standard electronic transfer between banks); transfers inside the same bank are faster.
7.4 How Rates Work: APY vs. APR
When you see a rate advertised as “4% APY,” that’s the Annual Percentage Yield: the total return if you leave your money untouched for a year. Interest compounds daily in most HYSAs, which means you earn interest on your interest.
Because APY already includes the effect of compounding, we don’t need to break it into daily pieces. The chart below follows the $9,600 emergency fund from Emergency Fund for five years at 4% APY, splitting each bar into the money you put in and the interest it has earned so far.
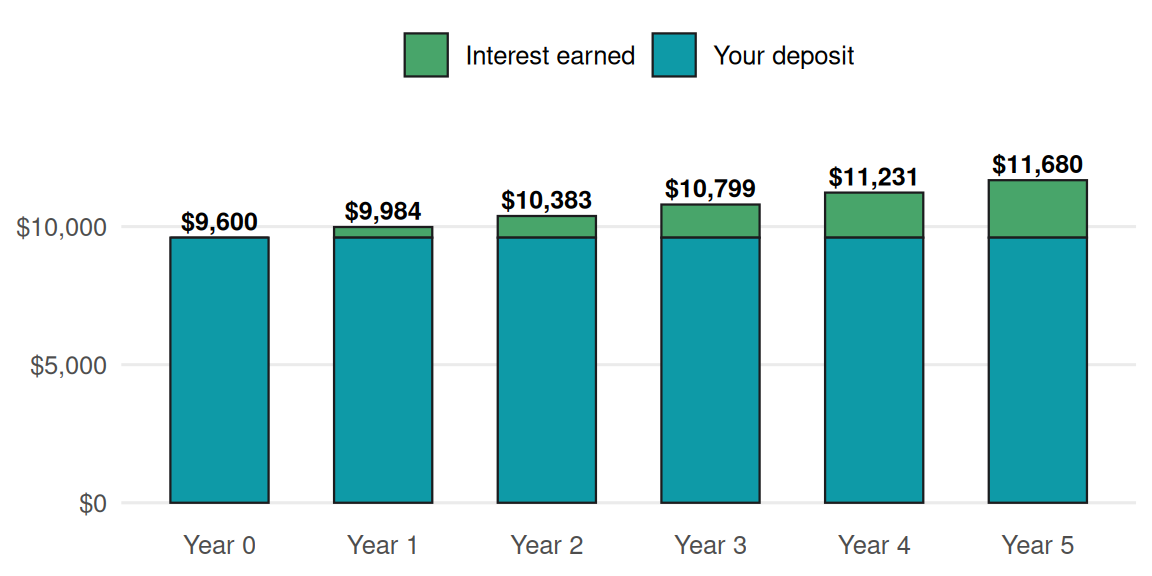
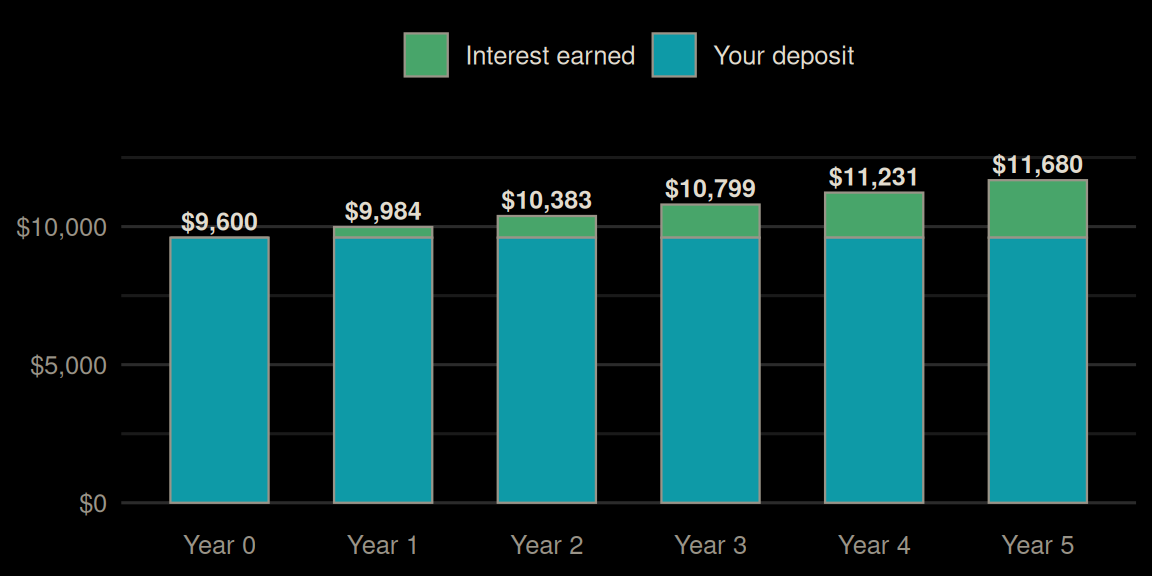
Each bar is the previous one multiplied by (1 + APY), so the green layer grows a little more each year. Multiplying by (1 + APY) once per year, for the number of years you hold the money, is the formula.
Formula: Ending Balance = Starting Balance × (1 + APY)^years
- Where: Starting Balance = the money you deposit, APY = the yearly rate after compounding, and years = how long you leave the money in.
(The daily math belongs to the APR, the rate before compounding: APY = (1 + APR ÷ 365)^365 − 1.)
Example: $9,600 in a 4% APY account after one year grows to:
$9,600 × (1.04) = $9,984.
Interest earned: $384.
Check: $9,984 ÷ 1.04 = $9,600, your starting deposit, and 4% of $9,600 is the $384 of interest.
Assuming Principal is in cell B2, Annual_APY is in cell C2, and Years is in cell D2:
=B2 * (1 + C2) ^ D2The Python version of hysa_balance() works the same way:
def hysa_balance(principal, annual_apy, years=1):
    return principal * (1 + annual_apy) ** years

# $9,600 at 4% APY after 1 year
print(round(hysa_balance(principal=9600, annual_apy=0.04, years=1), 2))
#> 9984.0

# Same money after 5 years
print(round(hysa_balance(principal=9600, annual_apy=0.04, years=5), 2))
#> 11679.87
In R, hysa_balance() grows a deposit at the APY for a given number of years.
hysa_balance <- function(principal, annual_apy, years = 1) {
  principal * (1 + annual_apy)^years
}

# $9,600 at 4% APY after 1 year
hysa_balance(principal = 9600, annual_apy = 0.04, years = 1)
#> [1] 9984

# Same money after 5 years
hysa_balance(principal = 9600, annual_apy = 0.04, years = 5)
#> [1] 11679.87
Notice that $9,600 at 4% becomes $9,984 after 1 year and $11,680 after 5 years. That’s growth without putting a single dollar of what you deposited at risk.
7.5 FDIC Insurance: What’s Covered
FDIC (Federal Deposit Insurance Corporation) insurance protects your money if the bank fails. Most online banks are FDIC-insured up to $250,000 per account holder per bank.
This means:
- A $10,000 HYSA balance is fully protected.
- A $500,000 balance? Only the first $250,000 is protected at that bank.
If you have more than $250,000 to save, open accounts at different banks. Each account gets its own $250,000 of protection.
7.6 How to Open a High-Yield Savings Account
Opening an account takes 10 to 15 minutes. Here are the steps:
Choose a bank from the table above (or verify current rates at DepositAccounts.com)
Visit their website and click “Open Account” or “Get Started”
Provide basic information:
- Name, address, date of birth, Social Security number
- Employment information (usually)
- Initial deposit amount (optional; many banks allow $0 to start)
Link your existing checking account for initial funding
Confirm the account via email or text (usually instant)
Fund the account with an ACH transfer (takes 1 to 2 days to arrive)
You’ll receive account and routing numbers via email. Hang on to these; you’ll use them to set up automatic transfers from your checking account to this HYSA.
Most banks have mobile apps. Once the account is open, you can transfer money through the app (takes 1 to 2 days) or schedule automatic transfers (set it and forget it).
7.7 Building Your Savings Hierarchy
Once you have a HYSA open, your savings structure looks like this:
- Emergency fund (3 to 6 months of essential expenses) → HYSA
- Sinking funds (car insurance, annual gifts, car maintenance) → HYSA
- Short-term goals (vacation in 6 months, down payment in 2 years) → HYSA or Money Market Account
- Mid-term goals (3 to 5 years) → CD or short-term bonds (loans to the government or companies that are paid back within a few years)
- Long-term goals (more than 5 years) → Investing (see Investing Basics)
%%{init: {'theme': 'neutral', 'themeVariables': { 'fontFamily': 'monospace', "darkMode":false, "fontSize":"16px"}}}%%

flowchart LR
    subgraph Short["<strong>Under 2 years</strong>"]
        EF("Emergency fund")
        Sink("Sinking funds")
        STG("Short-term goals")
    end
    subgraph Mid["<strong>3 to 5 years</strong>"]
        MTG("Mid-term goals")
    end
    subgraph Long["<strong>Over 5 years</strong>"]
        LTG("Long-term goals")
    end
    EF --> HYSA[("High-yield savings<br>or money market account")]
    Sink --> HYSA
    STG --> HYSA
    MTG --> CD[("CD or<br>short-term bonds")]
    LTG --> Inv[("Investing")]
    style EF fill:#0e9aa7,color:#F5F2E8,stroke:#1C1C1E,stroke-width:2px
    style Sink fill:#0e9aa7,color:#F5F2E8,stroke:#1C1C1E,stroke-width:2px
    style STG fill:#0e9aa7,color:#F5F2E8,stroke:#1C1C1E,stroke-width:2px
    style MTG fill:#0e9aa7,color:#F5F2E8,stroke:#1C1C1E,stroke-width:2px
    style LTG fill:#0e9aa7,color:#F5F2E8,stroke:#1C1C1E,stroke-width:2px
    style HYSA fill:#48a56a,color:#F5F2E8,stroke:#1C1C1E,stroke-width:2px
    style CD fill:#86ddcd,color:#1C1C1E,stroke:#1C1C1E,stroke-width:2px
    style Inv fill:#48a56a,color:#F5F2E8,stroke:#1C1C1E,stroke-width:2px
    style Short fill:#FFFFFF,color:#1C1C1E,stroke:#1C1C1E,stroke-width:2px
    style Mid fill:#FFFFFF,color:#1C1C1E,stroke:#1C1C1E,stroke-width:2px
    style Long fill:#FFFFFF,color:#1C1C1E,stroke:#1C1C1E,stroke-width:2px
Your HYSA is the workhorse of your savings. Once it’s funded and growing automatically (covered in Automating Savings), your money is safe, liquid, and earning enough to stay ahead of inflation.
7.8 Recap
- Open a high-yield savings account at an online bank. At around 4% APY, it can pay hundreds of times what a big bank’s basic savings account pays.
- The friction of a separate bank is a feature, not a bug. Those extra steps are what keep you from impulse spending.
- FDIC insurance protects up to $250,000 per bank. Your emergency fund is safe there.
- All major online HYSAs are similar. Don’t overthink it; pick one. The 0.1% to 0.4% difference between them is noise.
- Automate deposits to your HYSA. We’ll cover how in the next chapter.
Now that you know where to keep your savings, the next challenge is making sure money actually arrives there automatically, month after month, without relying on willpower. That’s what automating savings is all about.
The right account type matters more than most people realize. John Bogle’s principle of simplicity applies: you don’t need a complex strategy. You need safety, liquidity, and a rate that beats inflation. A high-yield savings account delivers all three.↩︎